

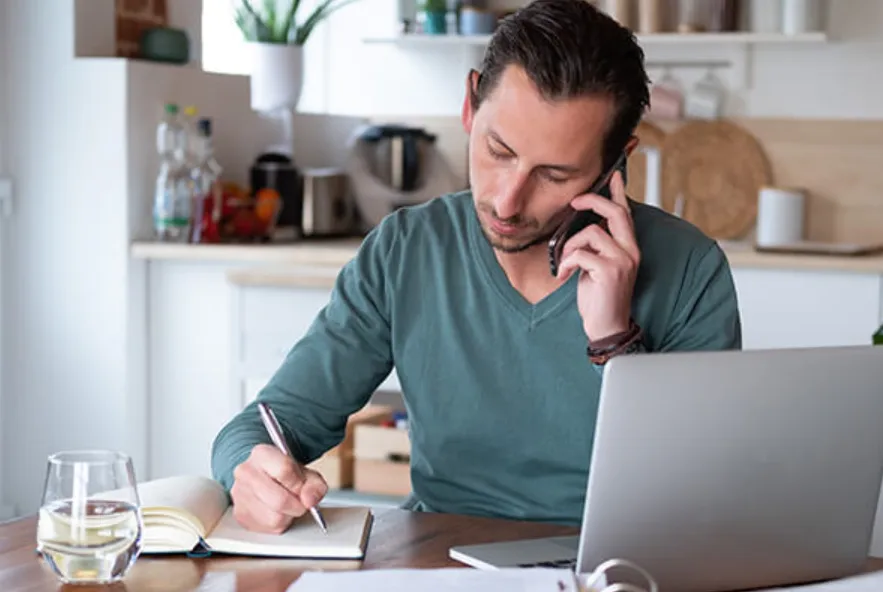
Your Words Can Become Part Of The Debt Story
When money gets tight and a creditor or debt collector reaches out, it is natural to want to explain yourself. You may want to sound responsible, cooperative, or honest. That instinct is understandable, but it can also work against you if you say too much before you know exactly who is contacting you, what they are claiming, and what rights you have.
Debt conversations are not casual chats. They are record building moments. Before discussing payments, hardship, or settlement options, it helps to understand the bigger picture, including issues like debt settlement taxes, written agreements, and how forgiven debt may affect your finances later.
Do Not Say, “Yes, That Debt Is Mine” Before Verification
The first thing to avoid is admitting responsibility for a debt before it has been verified. That does not mean you should lie. It means you should slow the conversation down.
Instead of saying, “Yes, I owe that,” say something like, “Please send me written verification of the debt.” A legitimate collector should be able to provide details about the original creditor, the amount owed, and your rights to dispute the debt.
The Consumer Financial Protection Bureau offers sample letters for communicating with debt collectors that can help you ask for more information in writing.
Do Not Promise Payments You Cannot Make
A promise may feel like a way to get off the phone, but it can create a new problem. If you tell a creditor, “I can pay $300 Friday,” and Friday comes without the payment, you may lose credibility and increase pressure on yourself.
Only agree to a payment plan after checking your budget. Rent, food, utilities, transportation, medicine, and insurance need to come first. A payment arrangement that collapses after one month does not solve the problem. It just adds stress.
A better phrase is, “I am reviewing my finances and need any proposed agreement in writing before I commit.”
Do Not Give Out Bank Account Details Casually
Never hand over checking account information just because someone asks for it. Giving direct access to your bank account can expose you to withdrawals you may not be ready for, especially if the agreement is unclear.
If you decide to make a payment, use a method you can control and document. Make sure the amount, date, creditor name, account number, and settlement terms are clearly written before money changes hands.
Do not rely on a verbal promise like, “Pay this today and we will take care of the rest.” Get the full agreement in writing first.
Do Not Overexplain Your Income Or Assets
It is tempting to explain every detail of your hardship. You may want to say, “I just got a raise,” “I have some savings,” or “I might sell my car.” Be careful. You do not need to provide a full financial map during an informal call.
Collectors may ask questions that sound conversational but are really about collectability. Your income, employer, bank, property, and assets are sensitive details. Share only what is necessary, and preferably in writing after you understand the situation.
A simple response is enough: “I am not prepared to discuss personal financial details by phone.”
Do Not Apologize In A Way That Sounds Like Admission
Saying “I’m sorry” feels polite, but in a debt conversation it can blur the line between courtesy and admission. You can be respectful without taking responsibility for something that has not been verified.
Instead of saying, “I’m sorry I did not pay this,” try saying, “I understand you are contacting me about an account. Please send the details in writing.”
That keeps the tone calm without giving away more than necessary.
Do Not Agree To A Settlement Without Written Terms
A settlement can be useful, but only if the terms are clear. Before agreeing, you need to know the exact amount being accepted, the payment deadline, whether the remaining balance will be forgiven, how the account will be reported, and whether the creditor will stop collection activity.
Verbal settlement offers are risky because memories differ and call notes may not protect you. Written terms protect both sides.
The Federal Trade Commission’s debt collection guidance for consumers explains important rules about how collectors may contact you and what they are not allowed to do.
Do Not Let Pressure Decide For You
Some collectors use urgency because urgency works. They may say an offer expires today, legal action is coming, or you must pay immediately. Sometimes those statements are real. Sometimes they are pressure tactics.
Either way, panic is not a plan. Ask for documentation. Review the dates. Confirm whether there is already a lawsuit or judgment. If legal papers have been served, respond by the deadline instead of relying on a phone call.
A calm sentence can help: “I do not make financial decisions during collection calls. Please send the information in writing.”
Do Not Ignore The Conversation Completely
Avoiding the wrong words does not mean saying nothing forever. Ignoring letters, lawsuits, or court notices can make things worse. Silence may lead to default judgments, wage garnishment, bank account levies, or additional fees.
The smarter approach is controlled communication. Use written correspondence. Keep copies. Send letters through trackable mail when appropriate. Take notes after calls, including the date, time, name of the representative, company, phone number, and what was discussed.
Say Less, Ask More, Get It In Writing
The safest mindset is simple: say less, ask more, and get everything in writing. You do not need to sound scared, ashamed, or overly friendly. You need to sound organized.
Good communication with creditors is not about winning an argument. It is about protecting your options. Before admitting, promising, paying, or sharing personal details, make the other side document the claim. Then you can decide what step makes sense based on facts instead of pressure.

Pun enthusiast, wordplay wizard, and the mastermind behind Funnnypuns.com. David turns everyday language into laugh-out-loud moments—one pun at a time!


Leave a Comment